

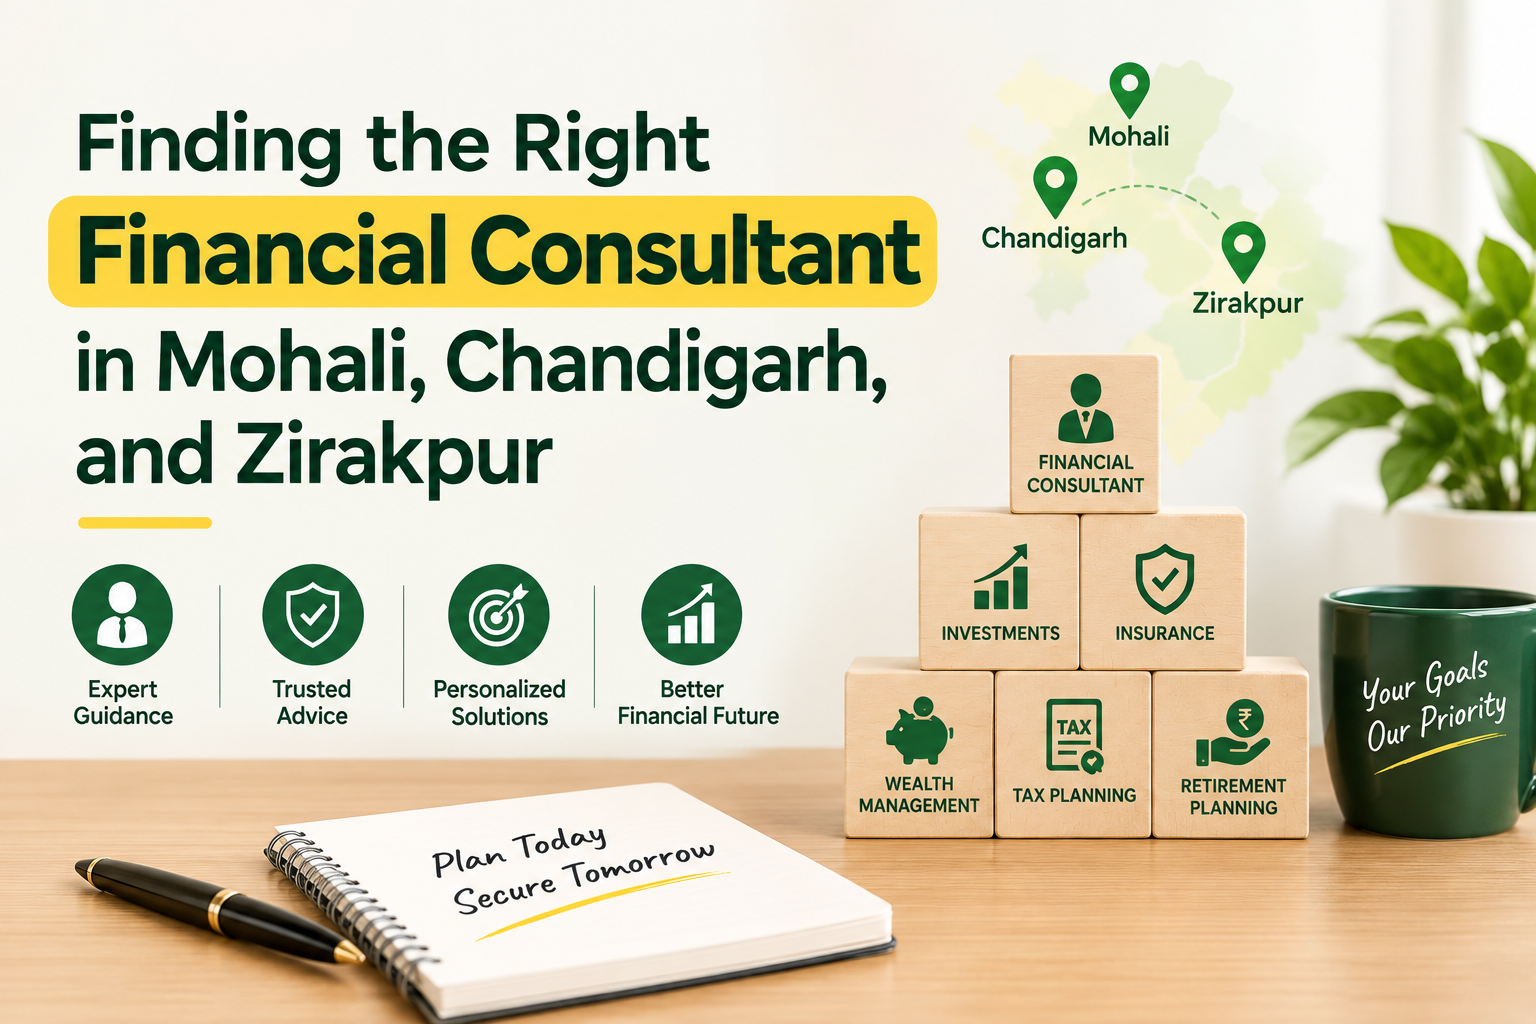
To find the right financial consultant in Mohali, Chandigarh, or Zirakpur, verify SEBI registration as a Registered Investment Adviser (RIA) or FPSB India Certified Financial Planner (CFP) credentials, prioritise fee transparency and fiduciary duty, match their expertise to your goals (wealth creation, tax planning, insurance, or portfolio management), check local experience and client reviews, and interview 2–3 candidates. Always cross-check registrations on official SEBI, AMFI, and IRDAI portals.
Key Takeaways
- Start with credentials: Prefer SEBI RIA (fiduciary duty) or CFP certification over pure commission-driven distributors.
- Clarify your needs first—retirement, child’s education, tax optimisation, health/life cover, or high-net-worth portfolio management.
- Local knowledge of Chandigarh Tri-city (Chandigarh–Mohali–Zirakpur) real-estate, tax, and lifestyle factors adds value.
- Demand a written financial plan, risk profiling, and regular reviews.
- Red flags include guaranteed returns, pressure tactics, and refusal to share registration numbers.
Why the Right Financial Consultant Matters in the Tri-City Area
Chandigarh, Mohali, and Zirakpur form one of North India’s fastest-growing urban corridors. Rising property prices, a strong professional and entrepreneurial population, increasing medical inflation, and growing awareness of mutual funds and SIPs have created strong demand for professional advice.
A good consultant helps you avoid costly mistakes, optimise taxes under current rules, select suitable products, and stay disciplined through market cycles.
Understanding the Different Types of Financial Professionals
Not every “financial advisor” is the same. Here’s a clear comparison:
| Type | Regulator / Body | How They Earn | Fiduciary Duty? | Best For |
|---|---|---|---|---|
| SEBI Registered Investment Adviser (RIA) | SEBI | Client fees only (capped) | Yes | Unbiased holistic planning & advice |
| Certified Financial Planner (CFP) | FPSB India | Fee or commission (depends on firm) | Only if also RIA | Goal-based life planning |
| Mutual Fund Distributor (MFD) | AMFI (ARN) | Trail commissions from fund houses | No | Executing mutual-fund investments |
| Insurance Advisor / Agent | IRDAI | Commissions from insurers | No | Health, life, and general insurance |
| Portfolio Manager (PMS) | SEBI | Management + performance fees | Contractual | High-net-worth portfolios (usually ₹50 lakh+) |
Benefits of Working with a Qualified Local Consultant
- Better tax efficiency and cash-flow management
- Proper risk profiling and asset allocation
- Guidance on Health Insurance in Chandigarh with high claim-settlement ratios and local hospital networks
- Access to or advice on best portfolio management services Chandigarh for larger corpuses
- Ongoing monitoring and rebalancing
- Claim support and policy servicing for insurance
- Local insight into Tri-city real-estate, education costs, and lifestyle expenses
Common Mistakes to Avoid
- Ignoring how the advisor is compensated
- Mixing insurance and investment products without understanding the difference
- Not demanding a written engagement letter or financial plan
- Skipping verification on SEBI, AMFI, or IRDAI websites
- Expecting guaranteed returns (a major red flag)
Expert Tips for Selecting the Right Consultant
- Always ask for the SEBI registration number (INA… format for RIAs) and verify it on the official SEBI intermediary portal.
- Look for experience with clients similar to you (salaried professionals, business owners, NRIs, or HNIs).
- Ask about their process for reviewing portfolios and insurance coverage annually.
- For larger portfolios, enquire about access to or recommendations for the best portfolio management services Chandigarh.
- Confirm they can help with Health Insurance in Chandigarh—comparing family floater plans, top-ups, and senior-citizen options with strong local cashless networks.
Step-by-Step Guide to Finding the Right Financial Consultant
- Define your goals and current situation
List short-term and long-term objectives, existing investments, insurance cover, income, expenses, and risk tolerance. - Decide the type of help you need
Comprehensive planning → prioritise CFP + RIA.
Mutual funds only → AMFI-registered MFD.
Insurance focus → IRDAI-licensed advisor.
Large portfolio (₹50 lakh+) → explore PMS options. - Search and shortlist
Use SEBI intermediary search, FPSB India CFP directory, AdvisorKhoj, Justdial, Google reviews, and local recommendations focused on Chandigarh, Mohali, and Zirakpur. - Verify credentials thoroughly
Cross-check SEBI RIA status, CFP certification validity, AMFI ARN, and IRDAI licence. Look for any disciplinary actions. - Interview 2–3 candidates
Ask about their process, fee structure, sample plans, client communication frequency, and experience with clients in the Tri-city area. - Review the engagement terms
Understand scope of service, fees, termination clauses, and conflict-of-interest disclosures. - Start with a written plan
Insist on a documented financial plan before implementing any products. - Schedule regular reviews
Agree on quarterly or half-yearly review cadence.
Comparison Table: Key Evaluation Criteria
| Criterion | What to Look For | Why It Matters |
|---|---|---|
| Registration | Active SEBI RIA or CFP + AMFI/IRDAI | Legal accountability & investor protection |
| Compensation | Transparent fee-only or clearly disclosed fee-based | Reduces product bias |
| Experience | 5–10+ years + local Tri-city clients | Practical knowledge of regional costs & taxes |
| Process | Risk profiling → goals → written plan → review | Structured, repeatable advice |
| Specialisations | Mutual funds, insurance, tax, PMS | Matches your specific needs |
| Client Reviews | Consistent 4.5+ ratings with detailed feedback | Real-world service quality |
| Communication | Regular reviews + accessibility | Long-term relationship success |
Actionable Checklist
- Written list of my financial goals and current assets/liabilities
- Verified SEBI / CFP / AMFI / IRDAI credentials of shortlisted advisors
- Understood and compared fee structures
- Asked for sample financial plans or case studies (anonymised)
- Checked recent client reviews specific to Chandigarh–Mohali–Zirakpur
- Confirmed ability to advise on Health Insurance in Chandigarh
- Scheduled first review meeting
Conclusion and Call to Action
Finding the right financial consultant in Mohali, Chandigarh, or Zirakpur is less about finding the “best” name and more about finding the professional whose process, credentials, and incentives align with your goals. Prioritise SEBI-registered or CFP-qualified advisors who demonstrate transparency, local understanding, and a willingness to put your interests first. Whether you need help with investments, tax planning, Health Insurance in Chandigarh, guidance from Certified financial planners in Chandigarh, or evaluation of the best portfolio management services Chandigarh, a structured selection process protects both your money and your peace of mind.
Take the first step today: list your goals, verify two or three professionals on official portals, and schedule discovery conversations.
Ready to move forward? Contact a verified local consultant for a no-obligation discussion, or visit official SEBI and FPSB resources to begin your shortlist. Your future self will thank you for the diligence you show now.
Frequently Asked Questions (FAQs)
1. How do I verify a financial consultant in Chandigarh or Mohali?
Check the SEBI intermediary portal for RIA registration, FPSB India directory for CFP status, AMFI website for mutual-fund distribution codes, and IRDAI agent registry for insurance licences.
2. What is the difference between a CFP and a SEBI RIA?
CFP is a professional certification focused on comprehensive planning. SEBI RIA is a regulated licence that imposes a fiduciary duty and restricts commission income from securities advice.
3. How much does a Certified Financial Planner charge in Chandigarh?
Fee-only planning typically ranges from a few thousand to around ₹1.25 lakh per year (SEBI-capped models vary). Many operate on a fee-based structure—ask for a clear breakdown.
4. How often should I review my plan with the consultant?
At least once a year, or more frequently after major life events (job change, marriage, property purchase, inheritance).
5. Is it better to go with a large national firm or a local Tri-city advisor?
Both can work. Large firms offer research depth; local advisors often provide more personalised attention and knowledge of Chandigarh–Mohali–Zirakpur realities. Evaluate process and alignment first.